


Implied Vol Solver
Inverse Black-Scholes: give it an option's price and it returns the implied vol that produces it, with every greek at that vol.
IVSOLVESOLVEAny inputs you type. Picking a coin with the asset picker fills live spot for BTC, ETH, SOL, HYPE and XRP; unlike BS, it takes no US tickers.
Typing it
IVSOLVE>IVSOLVE
Opens the solver. Enter spot, strike, days and a premium to get the IV.
What you see
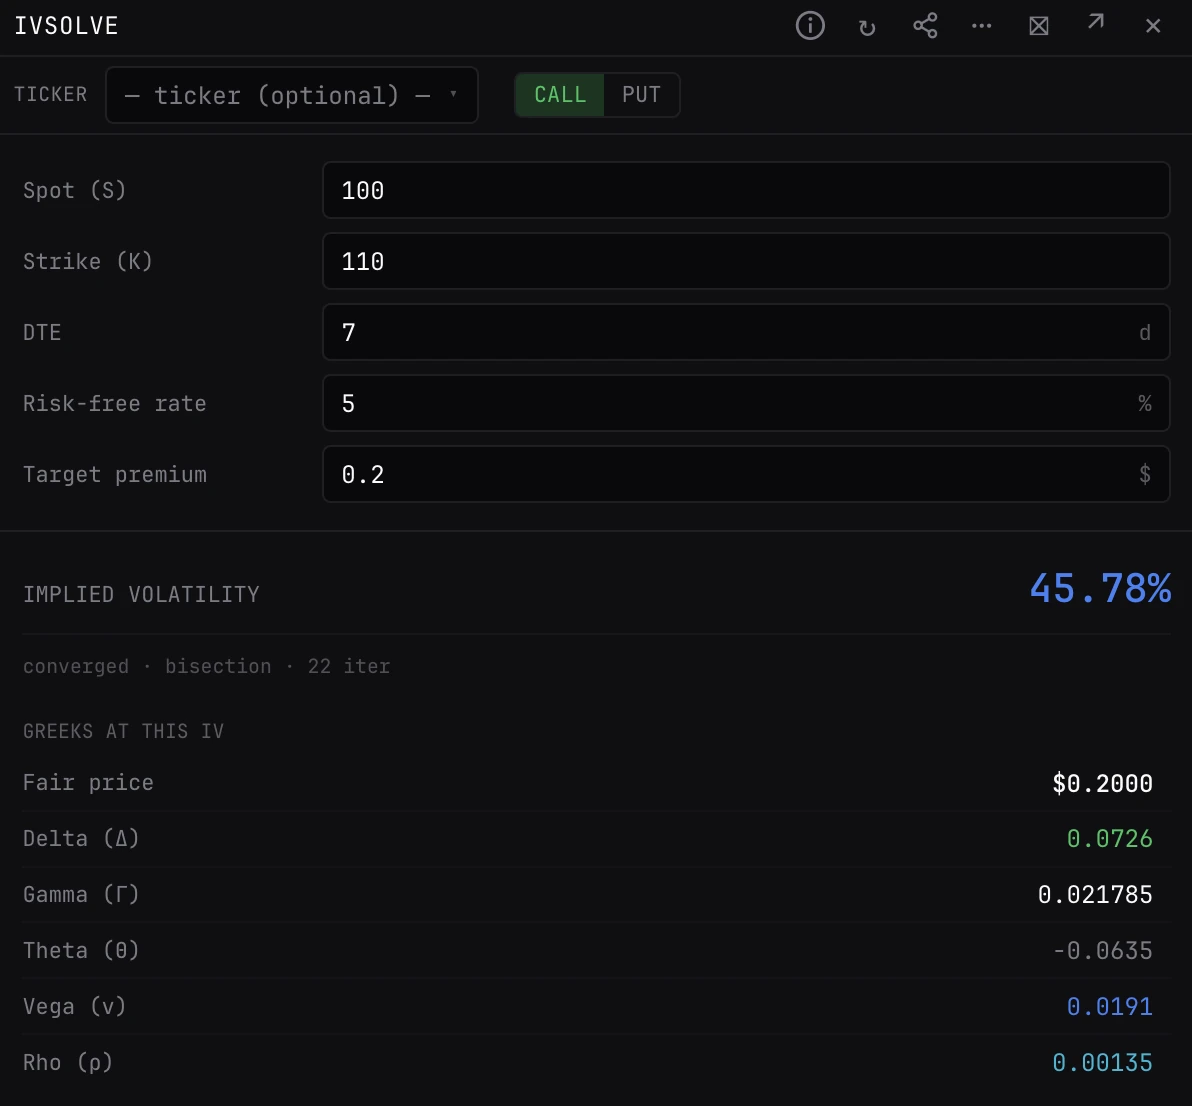
- Inputs. Ticker, CALL or PUT, Spot (S), Strike (K), DTE, Risk-free rate and Target premium.
- Implied Volatility. The solved IV, with how it got there: converged or clamped, the method and the iterations.
- Greeks at this IV. Fair price, Delta, Gamma, Theta, Vega and Rho for the side you picked.
How it solves
- Method. Newton-Raphson from an at-the-money first guess, falling back to bisection between 1% and 500% IV, so it converges on awkward inputs too.
- Floor. A premium below discounted intrinsic value has no IV.
- Cap. A premium at the no-arbitrage limit (spot for a call, the discounted strike for a put) reads 500%, clamped.
What to look for
- A quote's IV against the chain's at the same strike on CHAIN or SMILE: the gap is how rich or cheap the quote is.
Inputs
- Ticker
- Optional, crypto only: Ticker (optional) opens the asset picker on the option coins. Fills Spot from the live chain when Spot is empty.
- CALL / PUT
- The side. CALL is the default.
- Spot (S)
- The underlying price.
- Strike (K)
- The strike.
- DTE
- Days to expiry. 7 to start.
- Risk-free rate
- In %. 5 to start.
- Target premium
- The option price to solve for, in the same currency as spot.
Good to know
- The same Black-Scholes as BS: no dividend or carry, time in days over 365.
- A crypto option quoted in coin must be turned into dollars first: the premium in coin times spot.
- If no IV fits, the premium may be below intrinsic value, at the no-arbitrage limit, or so deep in or out of the money that the price barely moves with vol.
Pairs well with
Questions
What is it for?
Checking a quoted price. Solve its IV, then compare it with the live chain IV at the same strike on CHAIN or SMILE.
Why does it say no unique IV exists?
The premium is below intrinsic value, at the cap, or has almost no time value left, so no vol, or every vol, gives that price.
What does clamped mean?
The premium sits at the price an option reaches as vol goes to infinity, so the solver stops at its 500% ceiling.