


Black-Scholes Pricer
Fair value and every greek for a single call and put, side by side, priced off the live spot and at-the-money IV (ATM IV) when you pick a ticker, with a smile-adjusted price from the chain's 25 delta wings (the 25 delta put and call).
BSPRICERAny inputs you type. Picking a ticker fills spot and ATM IV from the live chain: BTC, ETH, SOL, HYPE and XRP options, and the 45 US options names (4 indices, 14 ETFs and 27 stocks).
Typing it
BSWhat you see
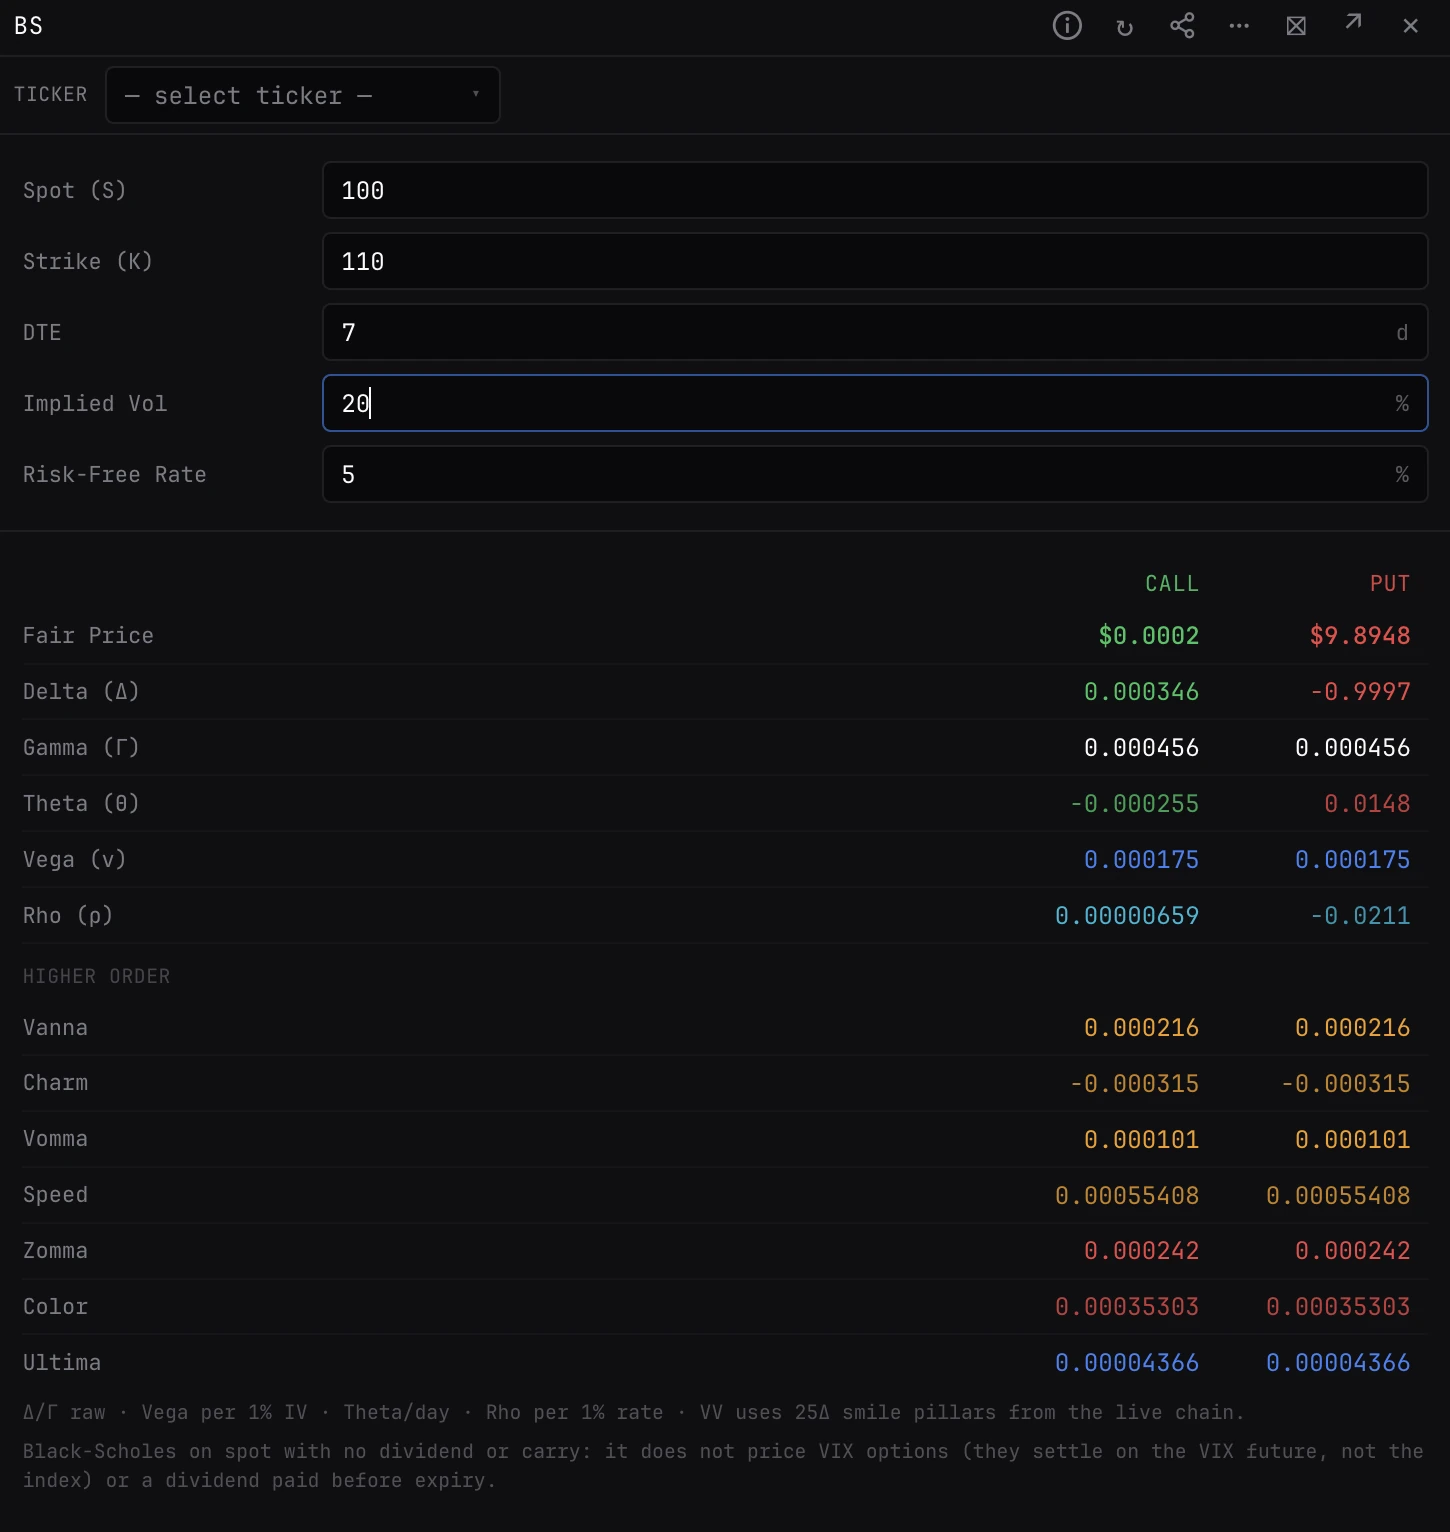
- Inputs. Ticker, Spot (S), Strike (K), DTE, Implied Vol and Risk-Free Rate. With a ticker picked, an empty Spot or Implied Vol uses the chain's live value.
- Call and Put. Fair Price, Delta, Gamma, Theta, Vega and Rho side by side.
- Higher Order. Vanna, Charm, Vomma, Speed, Zomma, Color and Ultima.
- Vanna-Volga Adjustment. VV Price, VV Adjust and Smile IV: the price the smile implies, from the chain's 25 delta put, ATM and 25 delta call vols, shown under the table.
How to read it
- Units. Delta and gamma are raw. Vega is per 1 point of IV, theta per calendar day, rho per 1 point of rate. Vanna and zomma are per 1 point of IV, vomma per point squared, ultima per point cubed.
- ATM IV. The prefilled vol is the at-the-money IV of the expiry nearest your DTE, so a 7 day and a 180 day price use different vols.
- VV Adjust. The smile's premium over the flat Black-Scholes price. Large on a wing strike, where a single ATM vol misprices.
What to look for
- How the greeks move as you change one input. It is the fastest way to build intuition for a structure.
- A quote against the VV Price: a wing that trades near the flat price, not the smile price, is cheap or rich against the smile.
Inputs
- Ticker
- Select ticker to start: it opens the asset picker on the assets with an options chain. A pick fills Spot and Implied Vol from its live chain and turns on the smile adjustment; × clears it.
- Spot (S)
- Empty to use the live spot.
- Strike (K)
- The strike to price.
- DTE
- Days to expiry. 7 to start.
- Implied Vol
- In %. Empty to use the live ATM IV.
- Risk-Free Rate
- In %. 5 to start.
Good to know
- Black-Scholes on spot with no dividend or carry, time in days over 365. It does not price VIX options, which settle on the VIX future, or a dividend paid before expiry.
- On the free plan the prefill reads the ticker late, a coin a day late and a stock at the last close, and the panel says so.
Pairs well with
IVSOLVESTRATEGYCHAINHEDGESMILE
Questions
Do I need to type spot and IV?
No. Pick a ticker and leave them blank. The pricer uses the live spot and the ATM IV of the expiry nearest your DTE.
What is the vanna-volga adjustment?
A standard way to add the smile to a Black-Scholes price: it reprices the option using the 25 delta put, ATM and 25 delta call vols. VV Adjust is the difference from the flat price.
Why is vega so small?
Vega is per 1 point of IV: the change in price if IV goes from 50% to 51%.