


Delta Exposure (DEX)
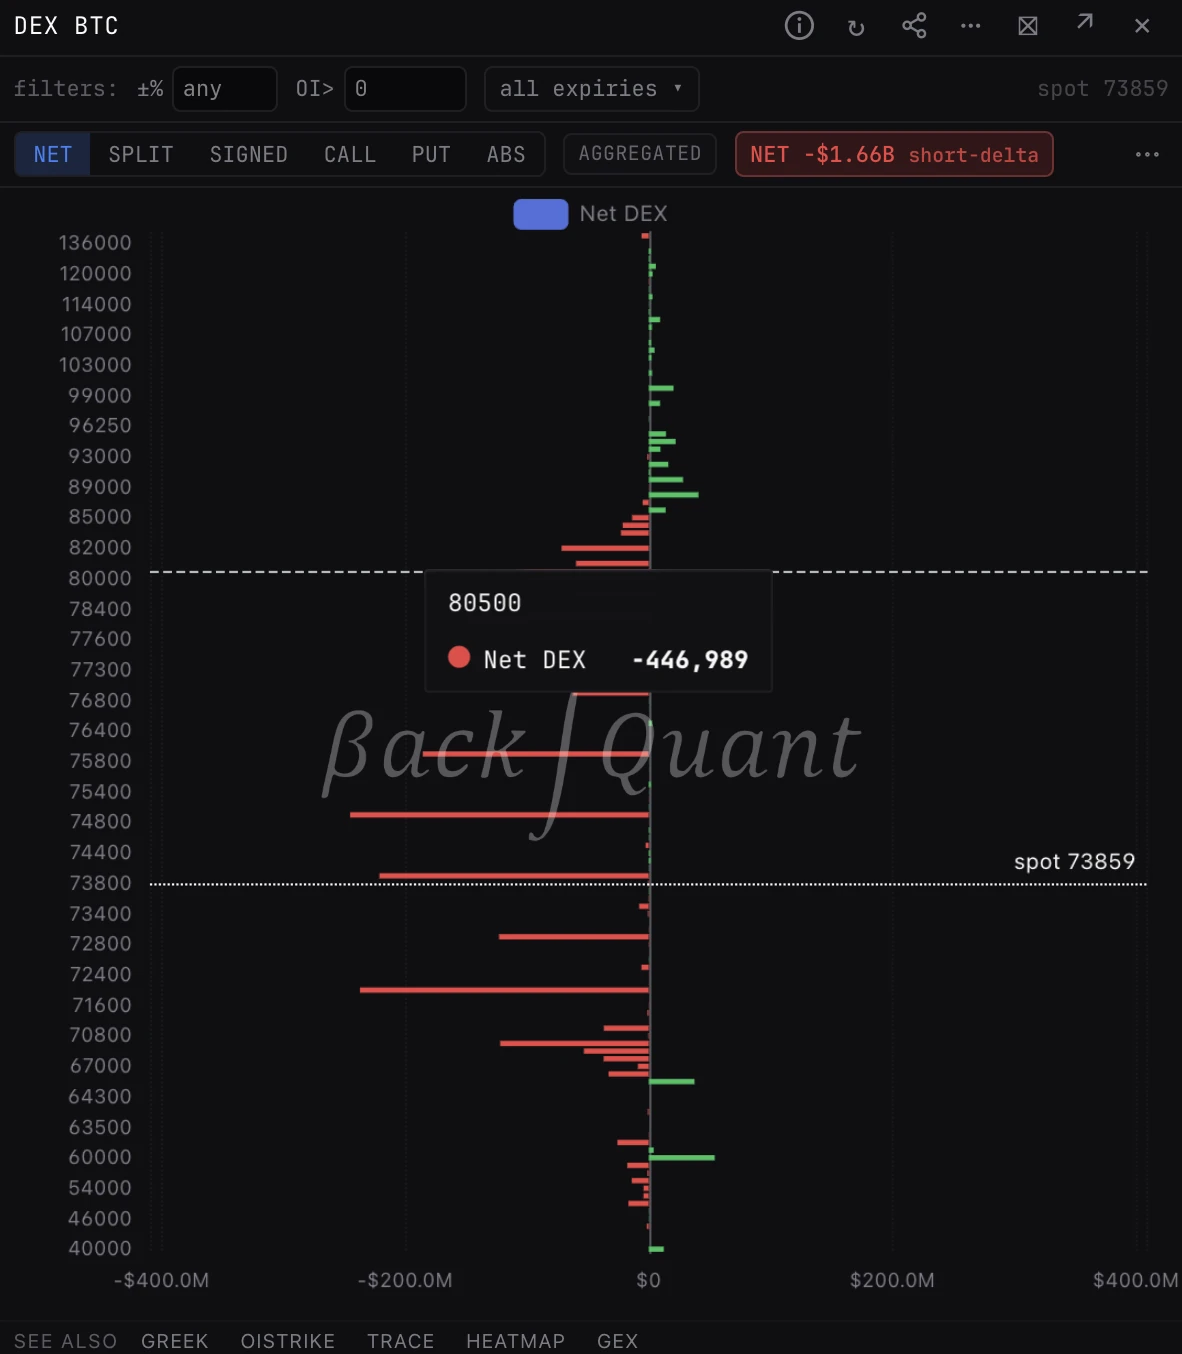
Option delta times open interest, summed at each strike: where the options book holds its directional risk. In BackQuant, DEX is shown from the customer side, so a positive bar means customers are net long delta at that strike and dealers hold the short side. A positive DEX is not bullish on its own: how dealers hedge as price moves depends on their gamma, so read it next to GEX.
Related terms
DeltaAn option Greek measuring how much the option price changes per one-dollar move in the underlying. A call with delta 0.5 gains roughly fifty cents per one-dollar rise in spot. Delta also approximates the probability the option finishes in-the-money.GammaA second-order Greek measuring how much delta changes per one-dollar move in the underlying. Gamma is highest for at-the-money options near expiry. Long option positions are always long gamma; short options are short gamma. Gamma is the input to gamma exposure.HedgeA position taken to offset risk in another position. Long spot can be hedged by buying puts. A short call book is hedged by buying delta in the underlying. Hedging defines market-maker behaviour and is the mechanical reason gamma exposure matters.LongA position that profits when price rises. Buying spot, going long a perp, owning a call, or being short a put are all long positions. Opposite of short.ShortA position that profits when price falls. Selling spot, going short a perp, owning a put, or being short a call are all short positions. Short positions in crypto carry tail risk because upside is unbounded.
See Delta Exposure (DEX) live on the terminal.
BackQuant is the analytics terminal for equity and crypto options. GEX walls, dealer positioning, options flow, and the full derivatives context - one product.