


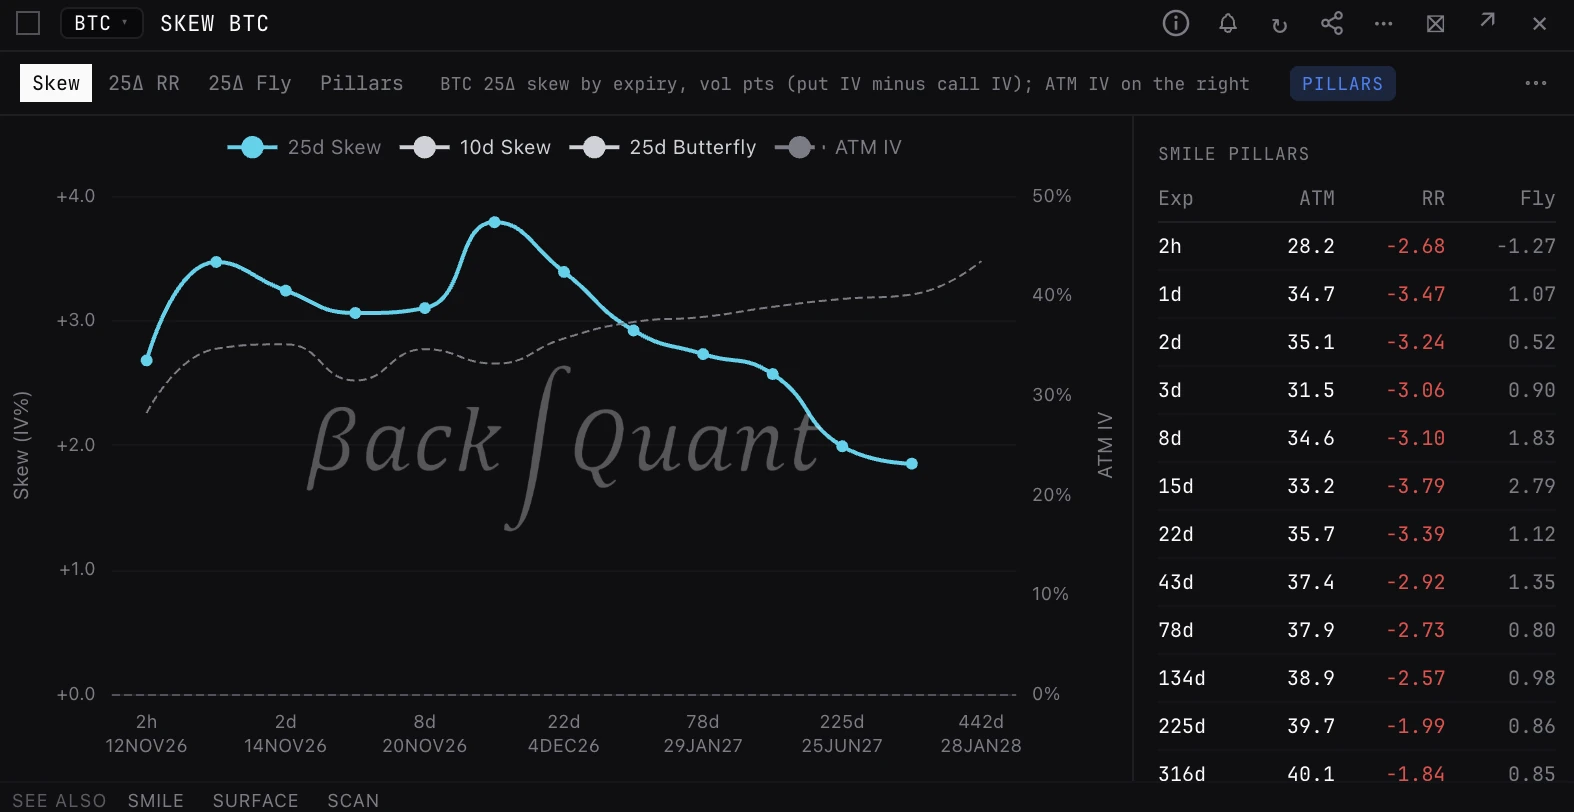
25 Delta Skew
The implied volatility of the 25 delta put minus the implied volatility of the 25 delta call for the same expiry. Positive means puts are richer than calls, the usual sign of demand for downside protection; negative means upside calls are bid. It is the risk reversal with the sign turned round, and the standard single number for how lopsided a smile is.
Related terms
DeltaAn option Greek measuring how much the option price changes per one-dollar move in the underlying. A call with delta 0.5 gains roughly fifty cents per one-dollar rise in spot. Delta also approximates the probability the option finishes in-the-money.ExpiryThe date and time at which an options contract settles. After expiry, an option pays out its intrinsic value or expires worthless. Crypto options on Deribit expire Fridays at 08:00 UTC.Risk ReversalCall implied volatility minus put implied volatility at the same delta, usually 25 delta. Negative means puts cost more than calls, the usual sign of downside hedging; positive means upside calls are in demand. As a trade, a risk reversal buys one side and sells the other, so it is a cheap way to express direction.0DTEZero days to expiration: options that expire the same day. They carry the most gamma for their time left, so dealer hedging on 0DTE positions can move spot sharply in the final hours before settlement. Crypto venues list daily expiries and US index options expire every trading day, so there is a 0DTE contract almost every day; tools that track 0DTE usually follow the nearest live expiry and roll to the next one after it settles.
See 25 Delta Skew live on the terminal.
BackQuant is the analytics terminal for equity and crypto options. GEX walls, dealer positioning, options flow, and the full derivatives context - one product.