

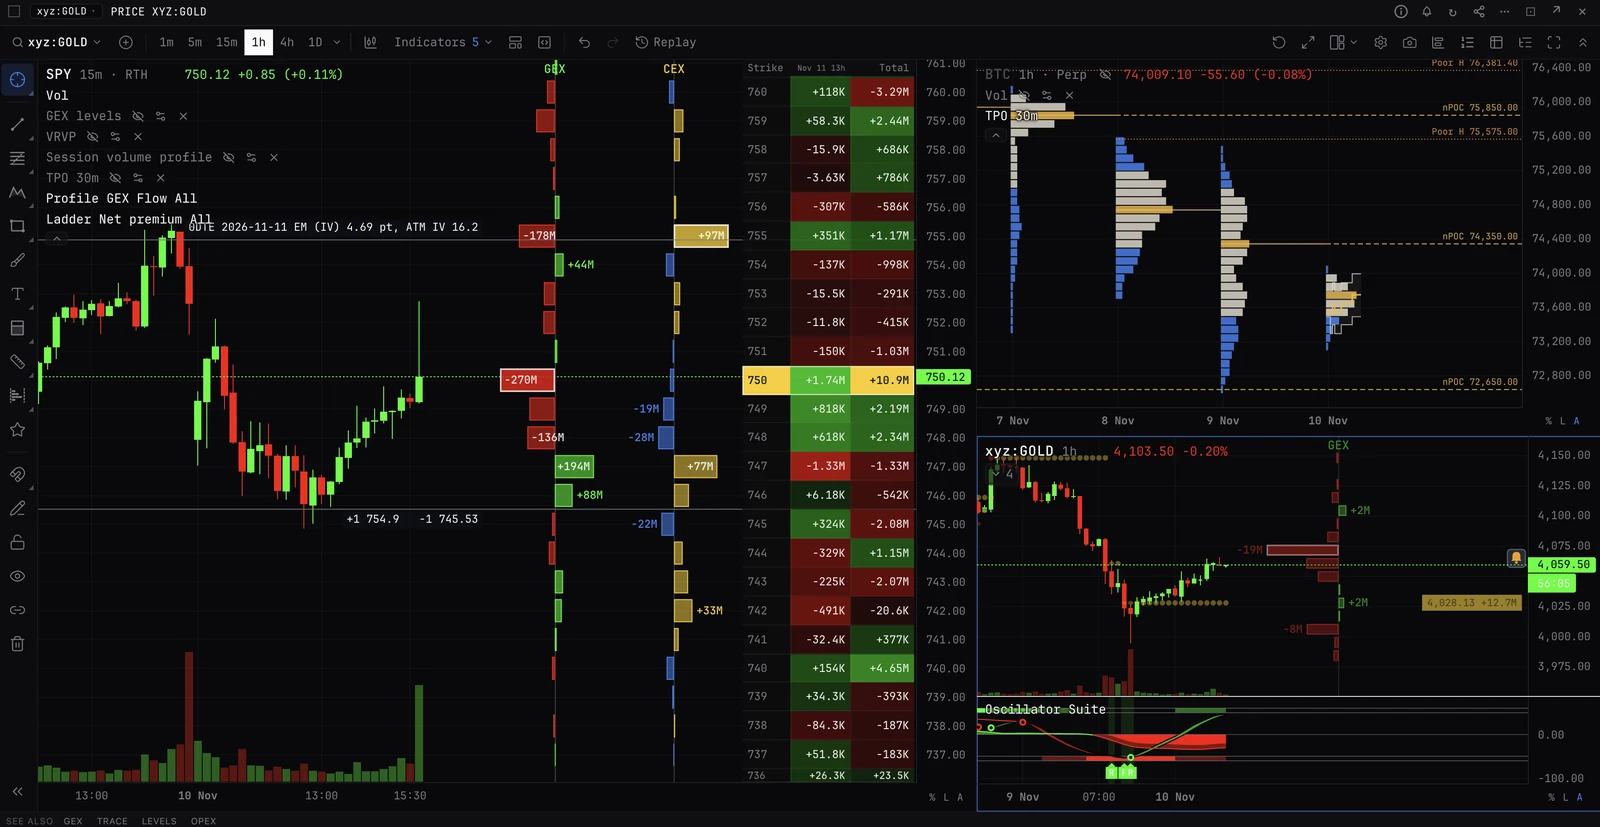
Dealer Hedging
The act of buying or selling the underlying to offset directional exposure created by an options book. Dealers stay delta-neutral by trading spot or perpetuals as price moves. Dealer hedging is the mechanical force behind gamma exposure effects, pinning, and OpEx flows.
Related terms
DeltaAn option Greek measuring how much the option price changes per one-dollar move in the underlying. A call with delta 0.5 gains roughly fifty cents per one-dollar rise in spot. Delta also approximates the probability the option finishes in-the-money.Delta-NeutralA position with offsetting deltas summing to zero, so small spot moves do not change the position value. Market makers run delta-neutral books by hedging continuously. Delta-neutral strategies isolate exposure to volatility, time decay, or higher-order Greeks.GammaA second-order Greek measuring how much delta changes per one-dollar move in the underlying. Gamma is highest for at-the-money options near expiry. Long option positions are always long gamma; short options are short gamma. Gamma is the input to gamma exposure.OpExOptions expiration: the moment a set of options settles. In crypto the largest expiries settle on Fridays at 08:00 UTC, with daily expiries in between; US equity and index options settle at the close, with the monthly expiry on the third Friday. Large expiries can move markets as dealers unwind their hedges, and quarterly expiries (March, June, September, December) are the largest of the year.SpotThe current cash market price of an asset for immediate delivery. Spot is the underlying reference for derivatives pricing. Crypto spot trades 24/7 across hundreds of venues, with index prices aggregating across the deepest ones.
See Dealer Hedging live on the terminal.
BackQuant is the analytics terminal for equity and crypto options. GEX walls, dealer positioning, options flow, and the full derivatives context - one product.