

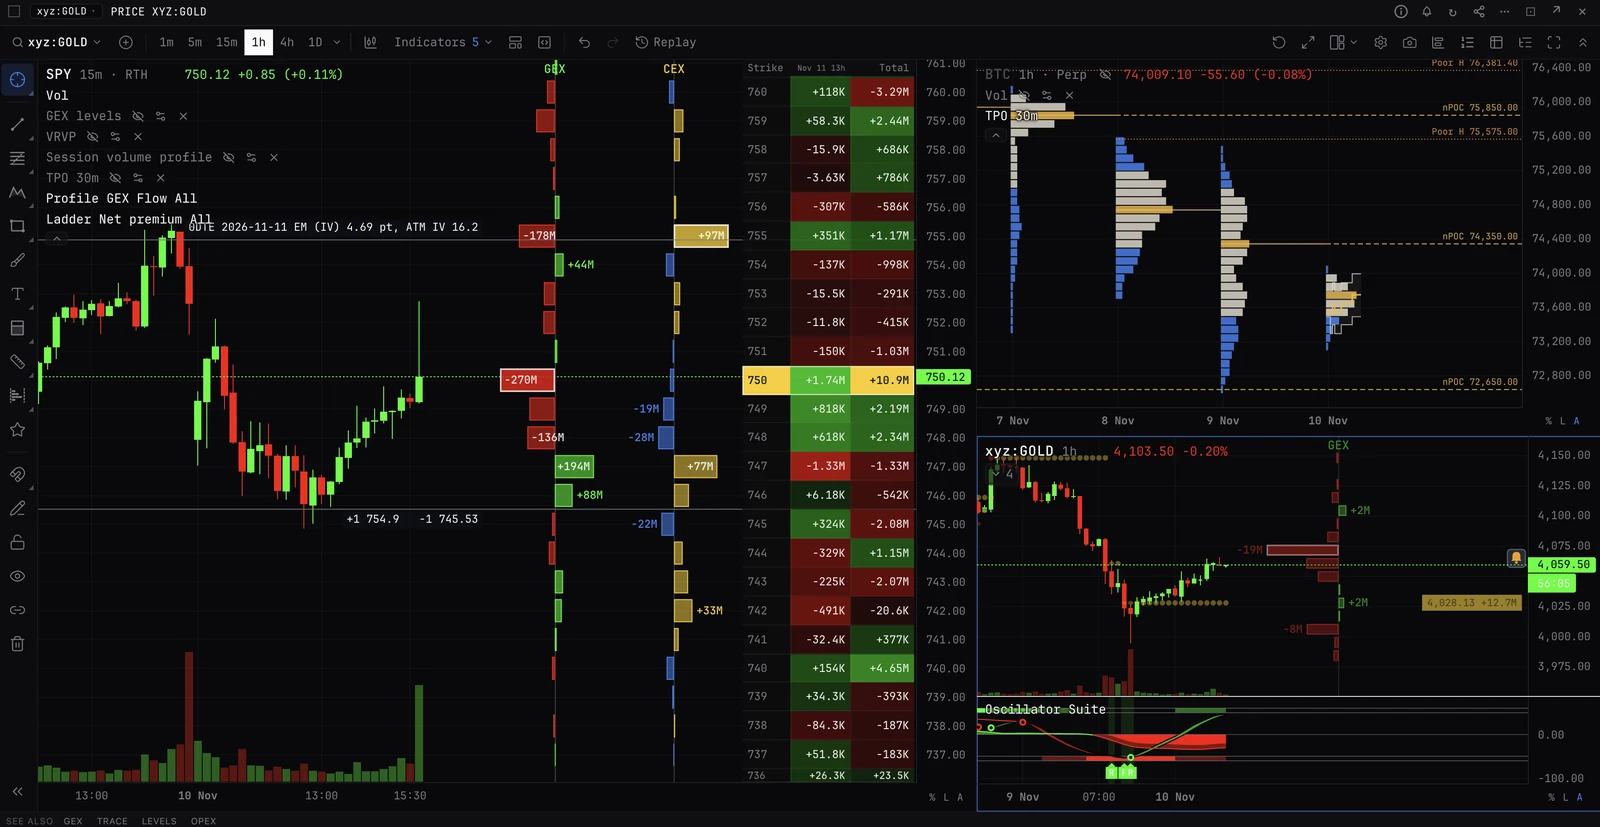
Charm
A second-order Greek measuring how an option's delta changes as time passes, with price and vol unchanged. Summed across a dealer book (charm exposure, CEX) it is the hedge the clock alone asks of dealers, in dollars of delta per day. It grows into expiry, which is why charm flows are strongest in the last hours before a large settlement.
Related terms
DeltaAn option Greek measuring how much the option price changes per one-dollar move in the underlying. A call with delta 0.5 gains roughly fifty cents per one-dollar rise in spot. Delta also approximates the probability the option finishes in-the-money.ExpiryThe date and time at which an options contract settles. After expiry, an option pays out its intrinsic value or expires worthless. Crypto options on Deribit expire Fridays at 08:00 UTC.HedgeA position taken to offset risk in another position. Long spot can be hedged by buying puts. A short call book is hedged by buying delta in the underlying. Hedging defines market-maker behaviour and is the mechanical reason gamma exposure matters.SettlementThe expiry-time process by which an option pays out its final intrinsic value. On Deribit, settlement occurs at 08:00 UTC using a half-hour time-weighted average of the index price. Settlement is the moment dealer hedging flows release.Call OptionA contract giving the holder the right (but not the obligation) to buy the underlying at a fixed strike price before or at expiry. Buyers profit when the underlying rises above the strike plus premium paid. Sellers collect premium and have an obligation to deliver if exercised.
See Charm live on the terminal.
BackQuant is the analytics terminal for equity and crypto options. GEX walls, dealer positioning, options flow, and the full derivatives context - one product.