

Realized Volatility
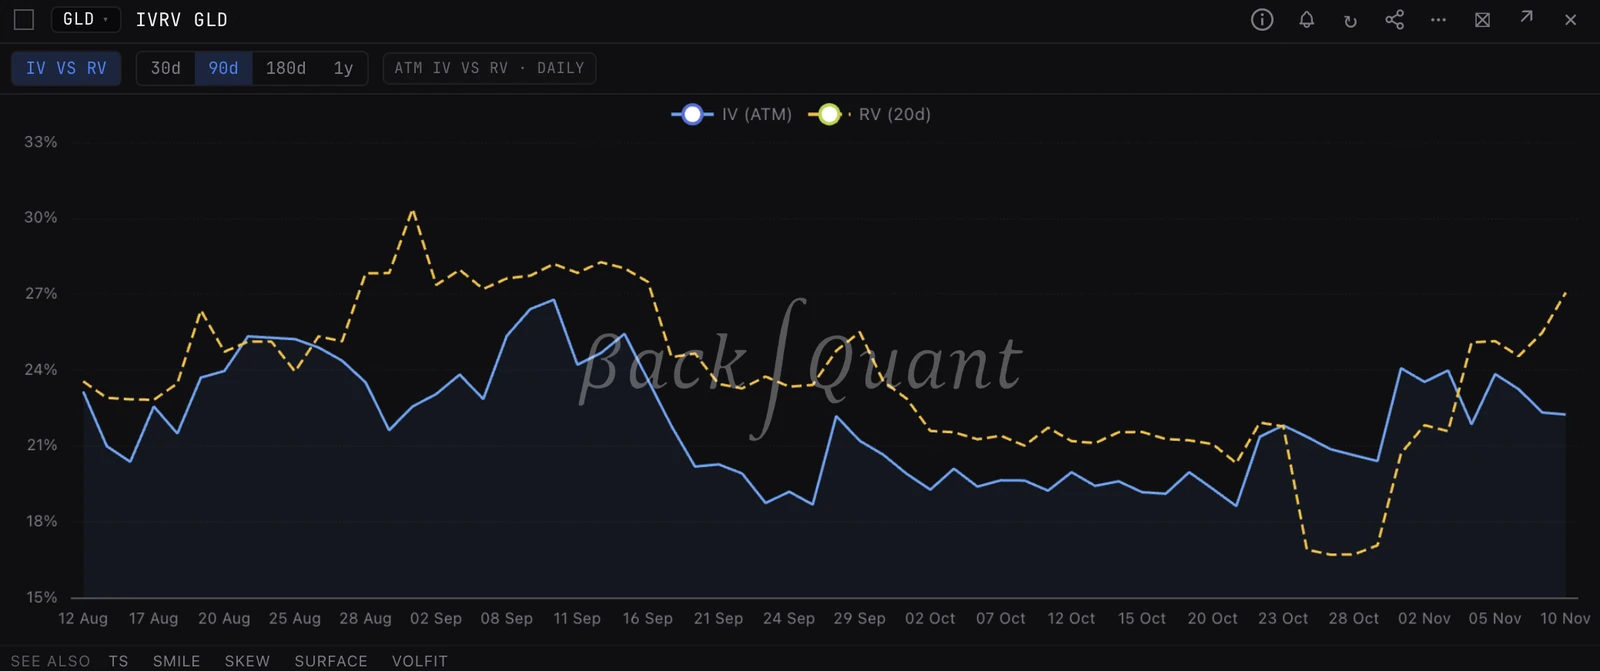
The volatility actually observed in the underlying over a window of time, calculated from historical price changes. The gap between implied and realized volatility is the volatility risk premium: historically, implied has usually run above realized, because option sellers want paying for tail risk. It is a tendency, not a guarantee, and it can flip sharply when markets are stressed.
Related terms
PremiumThe price of an option, paid by the buyer to the seller. Premium consists of intrinsic value plus time value. In a separate sense, basis premium refers to futures or perp prices trading above spot.Volatility Risk PremiumThe gap between implied volatility and the volatility that is later realized. Historically, implied has tended to sit above realized over long horizons, because option sellers want paying for tail risk, so the premium is usually positive. It is a tendency, not a promise of profit: it can vanish or invert in stress regimes, and selling options carries large losses when it does.RangeA price regime bounded by clear support and resistance, with mean-reverting behaviour inside. Ranges are most likely in positive-gamma environments and tend to compress as expiry approaches.RegimeThe character of price action over a period: trending or ranging, high-vol or low-vol, positive or negative gamma. Regime classification is the single most important input to strategy selection. A signal that works in one regime often fails in another.ResistanceA price level where selling pressure has historically appeared and price has stalled or reversed. Strong resistance often coincides with call walls, max pain, prior highs, or round numbers. A confirmed break of resistance often produces follow-through.
See Realized Volatility live on the terminal.
BackQuant is the analytics terminal for equity and crypto options. GEX walls, dealer positioning, options flow, and the full derivatives context - one product.